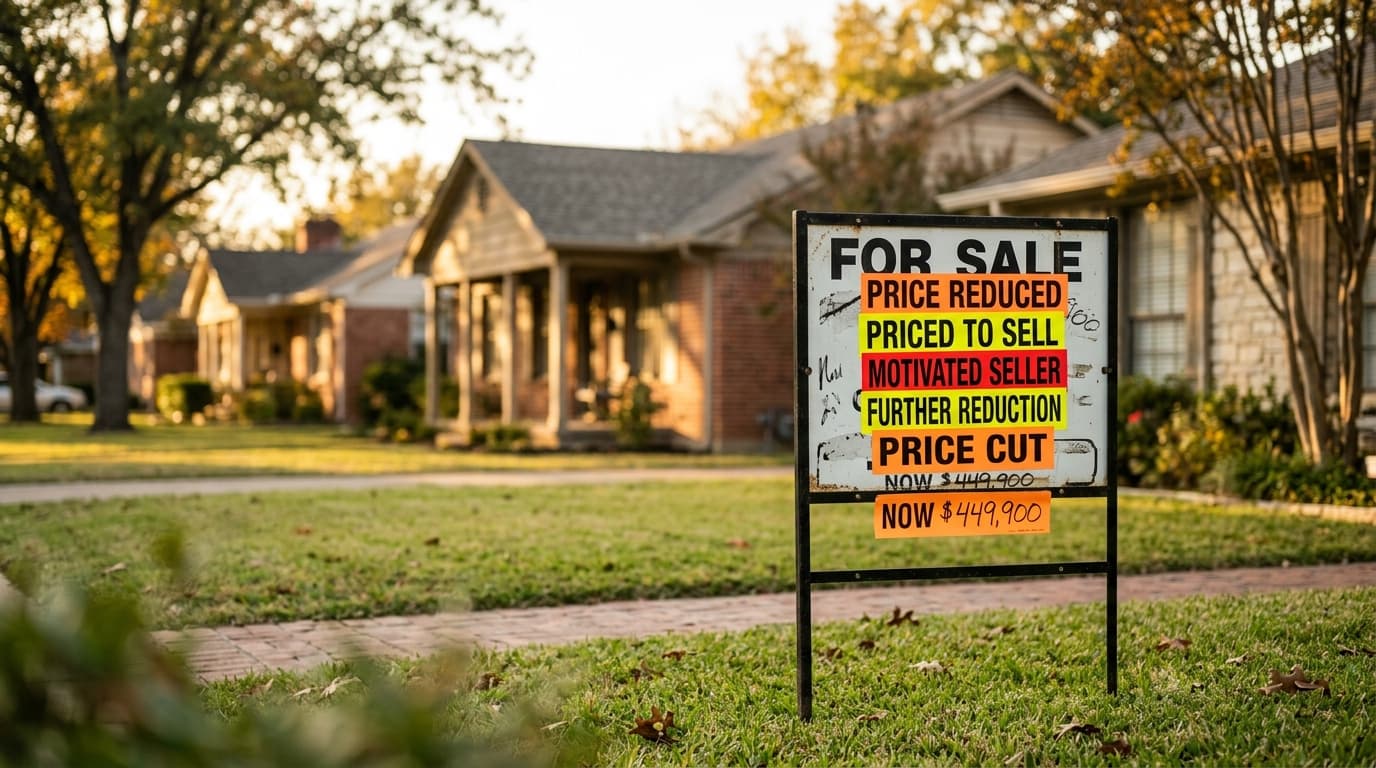
Dallas-Fort Worth Buyer Leverage 2026: How to Use Inventory to Negotiate Price Concessions
With roughly 29,600 active listings and a seller-to-buyer ratio near 2:1, Dallas-Fort Worth buyers in 2026 have real leverage for the first time since 2019 — but that leverage only pays off if you negotiate price, credits, and repairs deliberately instead of aggressively.
Think of it like a garden that's finally been over-planted. There are more seeds in the ground than there are hands to pick them. That's good news if you're one of the pickers — but only if you know which fruit is ripe and which vine is still stubborn.
The Numbers Behind the Shift
For years, DFW buyers competed in tight rows with barely a listing to spare. Now the field has widened. A 2:1 seller-to-buyer ratio means sellers are, on average, outnumbering serious buyers two to one — a meaningful shift from the scramble years. That doesn't mean homes are giving themselves away. It means the soil has softened enough that reasonable requests can actually take root.
How to Use Your Leverage (Without Overplaying Your Hand)
Leverage is like sunlight — helpful in the right dose, damaging in excess. Buyers who walk in demanding the moon often watch a seller simply wait for the next offer instead. The goal isn't to win every point; it's to walk away with a fair harvest.
Start by understanding why a listing has sat. A home priced right but stale from low showings behaves differently than one that's overpriced and stubborn. Your agent or broker team can help you read those signals before you plant your offer.
Three Negotiation Levers Worth Pulling
- Price. With more inventory, you can anchor closer to comparable sales rather than list price — but bring data, not just a lowball guess.
- Repair credits. If an inspection turns up aging roots — an older roof, foundation settling, outdated systems — ask for a credit instead of insisting the seller fix everything themselves. Credits are often easier for sellers to say yes to.
- Closing cost concessions. Some sellers would rather help cover costs than drop price, since it doesn't dent their bottom line on paper the same way. This can pair well with certain down payment assistance or first-time buyer programs, subject to qualification.
The Line Between Smart and Greedy
Every garden has a growing season, and every negotiation has a window. Push too hard, too long, and a seller who was ready to work with you may simply let the listing sit for the next bloom. The sweet spot is asking for what the inspection and comps actually support — not everything you can think to ask for.
A good rule: negotiate the things that affect the home's function or value (repairs, price, credits), and let the small cosmetic stuff go. That's where deals either take root or wither.
Rooted in Texas: What This Means Across the State
DFW's shift is part of a broader pattern across Texas, where inventory has been loosening in several metro areas. That doesn't mean every neighborhood behaves the same way — some pockets are still tightly wound, others wide open. Understanding your specific micro-market matters more than the headline stat.
Building Your Offer With a Broker Who Shops for You
Negotiating leverage is only half the map. The other half is making sure your financing is structured to support the offer you're making — whether that means flexibility on closing timelines, seller credits, or program eligibility. As a mortgage brokerage, Plan Prepare Home doesn't lend the money directly; instead, we shop multiple lenders on your behalf to find options that fit your specific offer strategy, programs subject to qualification.
Because leverage without a solid plan behind it is just a nice-looking seed packet. Pairing the two — market timing and the right financing structure — is what actually turns into fruit.
Ready to make a plan?
- Start your plan: planpreparehome.com/apply
- Apply now: pph.pub/apply
- Call or text: 619-777-5700
Worth reading next: Dallas-Fort Worth Home Buyer Negotiation 2026: How…, Dallas Fort Worth Housing Market 2026: Falling Prices,… and How to Make an Offer on a House in Austin, Texas in…. For the local picture, see our Texas page.