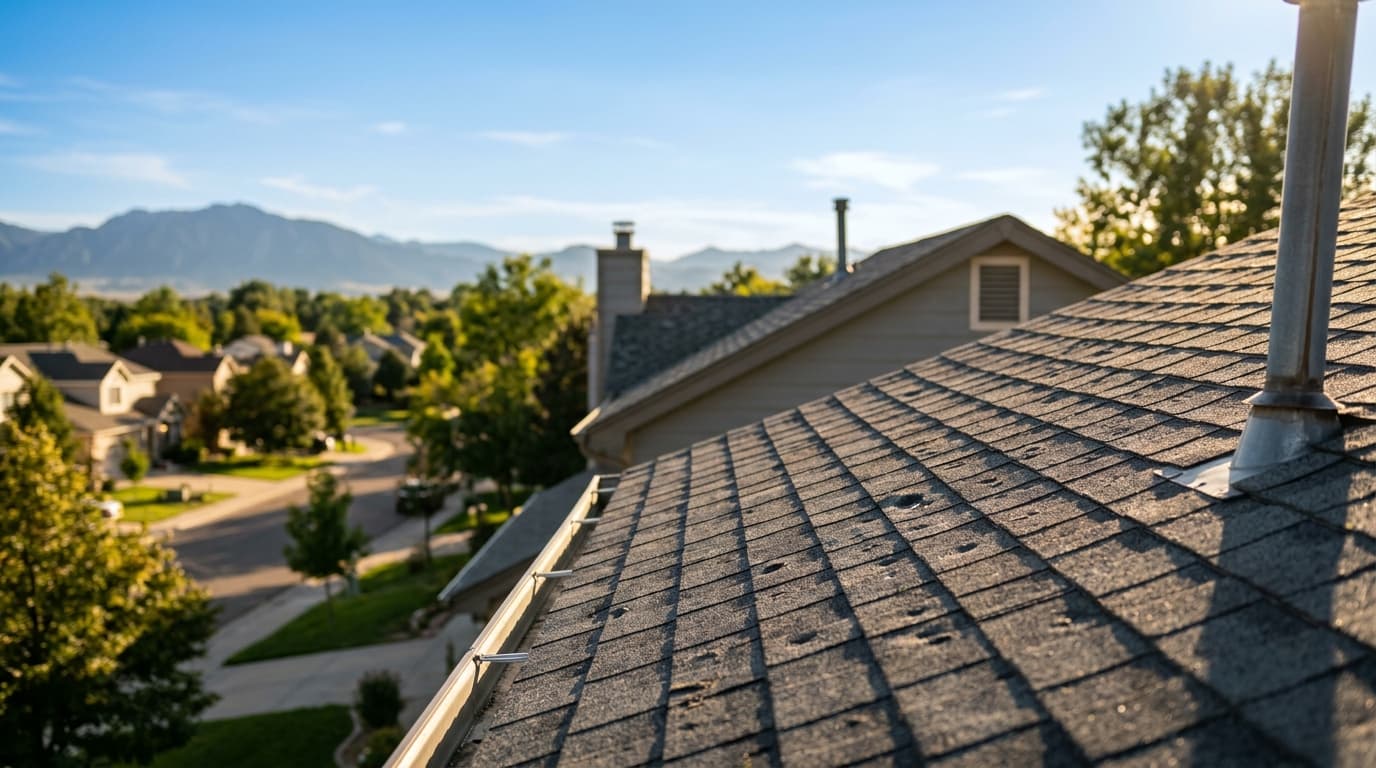
Colorado Springs Insurance Costs Homebuyers 2026: Why Your Monthly Payment Math Needs a Second Look
Colorado Springs homebuyers in 2026 are seeing insurance costs climb sharply — in many cases adding $150–$400 or more to monthly housing costs — driven by repeated hail events and growing wildfire exposure across El Paso County, and that shift changes how much home a buyer can comfortably qualify for.
If you've been house-hunting along the Front Range, you've probably heard the phrase "insurance shock" tossed around at open houses. It's not hype. It's math — and it's math that belongs in your affordability conversation from day one, not after you're already under contract.
The Hail & Wildfire Squeeze in El Paso County
Colorado Springs sits in one of the most hail-prone corridors in the country, and the last several storm seasons have left insurers recalculating risk on nearly every rooftop in the region. Layer in wildfire exposure from the foothills and open grasslands nearby, and you get a market where carriers are tightening coverage, raising deductibles, or stepping away from certain ZIP codes altogether.
Think of it like soil erosion — it happens gradually, then all at once. A home that had modest, predictable insurance costs a few years ago may now carry a premium that's doubled, simply because the "ground" underneath the risk models has shifted.
What This Means for Your Monthly Budget
Here's the part that catches buyers off guard: insurance isn't a side expense. It's baked directly into your monthly housing payment alongside principal, interest, taxes, and (often) HOA dues. When a lender or broker calculates your debt-to-income ratio, a higher insurance premium raises your total monthly obligation — which can shrink the loan amount you qualify for, even if your income and credit profile haven't changed at all.
In practical terms, a buyer who assumed a certain price range six months ago may find that same price range now sits just out of reach once a realistic insurance estimate is plugged in. It's not about your creditworthiness — it's about the roof over your head needing a bigger umbrella.
How to Plant Insurance Into Your Affordability Equation Early
The smartest move is to treat insurance like a seed you plant before you ever make an offer, not an afterthought you discover at closing. A few ways to do that:
- Get a real quote before you fall in love with a house. A rough estimate from an insurance agent familiar with El Paso County conditions can save you a heartbreak later.
- Ask about the roof's age and material. Older or impact-vulnerable roofing often drives premiums up significantly.
- Factor wildfire mitigation into your search. Defensible space, non-combustible siding, and proximity to open land all influence coverage availability and cost.
- Build a buffer into your pre-approval conversation. A good broker will stress-test your numbers with a realistic insurance range, not just a placeholder figure.
This is where working with a broker (rather than a single lender) pays off — we shop multiple lending options and help you see the full affordability picture, insurance included, so there are no surprise storm clouds at the closing table.
Programs and Options Worth Exploring
Depending on your situation, there may be loan programs designed to accommodate higher carrying costs or help you structure your budget around a changing insurance landscape — programs subject to qualification. The right fit depends on your income, the property itself, and how the insurance picture shakes out for that specific address. This is exactly the kind of detail worth mapping out with a broker early, rather than discovering it mid-contract.
The Takeaway: Root Your Plan in Real Numbers
Colorado Springs is still a beautiful, growing place to put down roots — but 2026 buyers need a clearer map of total housing costs, insurance included, before they start planting. A realistic pre-approval conversation that accounts for today's insurance climate helps you shop with confidence instead of chasing a number that quietly shifts underneath you.
If you're exploring homeownership anywhere along the Front Range or across the state, our Colorado page is a good starting point for understanding how local market conditions — insurance included — factor into your overall plan.
Ready to make a plan?
- Start your plan: planpreparehome.com/apply
- Apply now: pph.pub/apply
- Call or text: 619-777-5700
Worth reading next: How Much Does Hail Insurance Cost Denver Colorado Home…, Colorado Homeowners Insurance Hail Cost Monthly… and Colorado Hail Insurance Cost for Homebuyers 2026: What…. For the local picture, see our Colorado page.