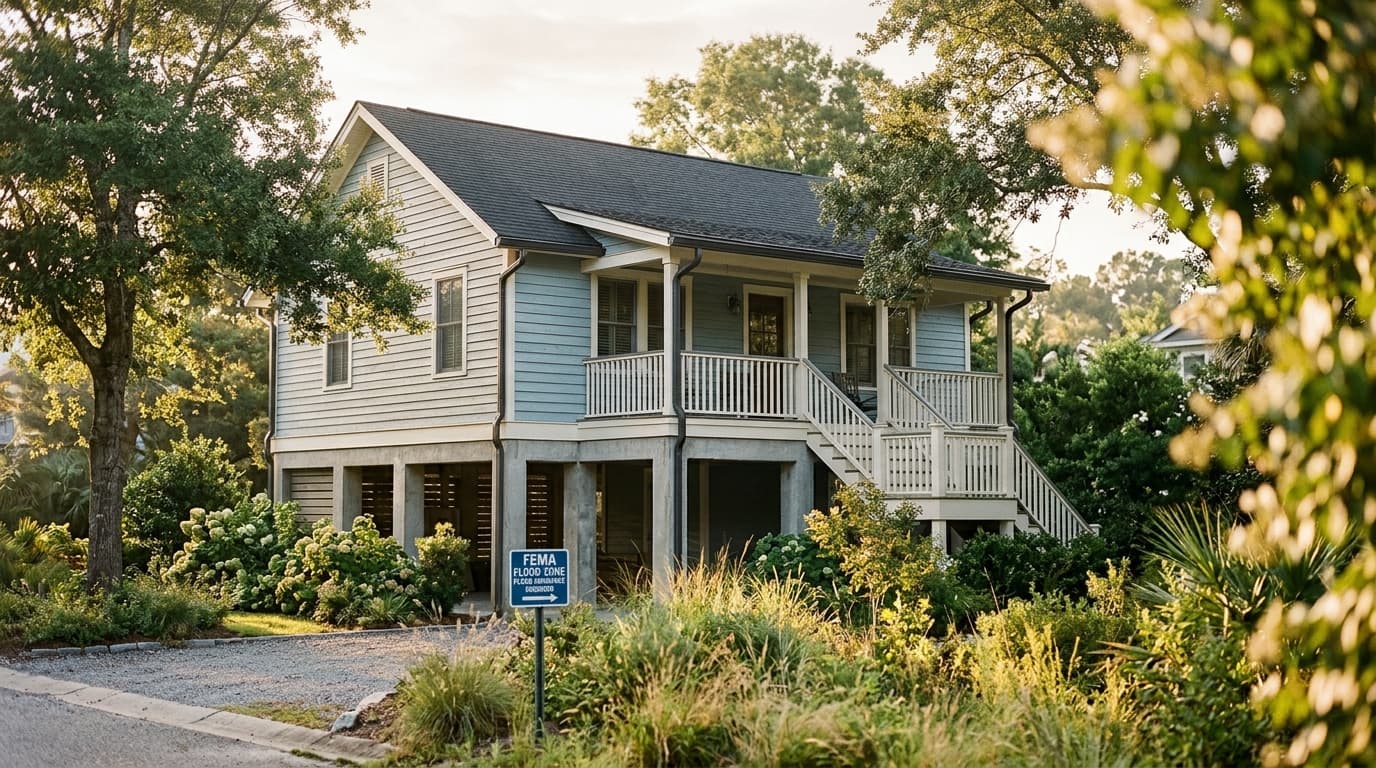
Houston Texas Flood Insurance Cost & Homebuying: What Your Appraisal Won't Warn You About
Houston flood insurance costs vary enormously by property, flood zone designation, and elevation, often adding a meaningful monthly expense that buyers must factor into their true housing budget before making an offer. Unlike most Texas metros, Houston's flat terrain, bayou network, and post-Harvey flood mapping updates mean flood insurance isn't a footnote here — it's a core part of the underwriting conversation.
Why Houston Is Different From the Rest of Texas
Dallas, San Antonio, Austin — these markets occasionally touch flood zones, but Houston lives with them. The city's bayous, clay soil, and low elevation create a patchwork of FEMA flood zones that can change block by block, sometimes even lot by lot. After Hurricane Harvey, FEMA revised many flood maps across Harris County, which means a home that wasn't in a flood zone a decade ago might be today — and vice versa.
This matters because flood zone status often determines whether flood insurance is required as a condition of the loan, not just recommended. When a lender's underwriting file shows a property sitting in a Special Flood Hazard Area (SFHA), mandatory flood insurance usually becomes part of the deal.
The Appraisal Doesn't Tell the Whole Story
A standard appraisal confirms value and condition — it doesn't price out your flood insurance premium or explain how that premium interacts with your monthly payment. That's a separate planning step, and it's one many out-of-state buyers (and even some local ones) skip until it's too late in the process.
Before writing an offer, it's worth pulling the FEMA flood map for the specific address, not just the neighborhood. Elevation certificates, base flood elevation data, and the home's foundation type (slab vs. pier-and-beam) all influence the eventual premium. Two homes across the street from each other can land in different flood zones entirely.
Pricing Flood Insurance Into Your True Monthly Cost
Think of your mortgage payment like a garden bed — the loan payment is the soil, but flood insurance, property taxes, and homeowners insurance are the water and nutrients that determine whether the whole thing actually thrives within your budget. Skipping that math is like planting without checking the sun exposure first.
When evaluating a Houston property, ask your broker to help model total monthly housing cost — not just principal and interest, but estimated flood insurance, standard homeowners coverage, and taxes together. Plan Prepare Home works as a broker, shopping multiple lenders and loan structures to find financing options that fit your full budget picture, not just the loan amount. Programs subject to qualification, loan structures can sometimes be arranged to accommodate escrowed insurance costs more comfortably within your overall payment plan.
Negotiating Seller Credits for Flood Risk
Here's where Houston buyers have real leverage. If a flood zone designation or elevation issue surfaces during due diligence, it's entirely reasonable to request a seller credit toward closing costs or an insurance reserve. Sellers in flood-prone areas often expect this conversation, especially if the home has a flood history disclosed on the Seller's Disclosure Notice.
A seller credit won't erase the ongoing premium, but it can soften the upfront shock — much like staking a young tree to help it stand through its first storm season. Your real estate agent and broker can work together to structure this request so it doesn't jeopardize the offer's competitiveness.
Questions Worth Asking Before You Offer
- What flood zone is this specific address in, per the current FEMA map?
- Has the home flooded before, and is that disclosed?
- What's the foundation type, and has it been elevated?
- What would flood insurance plus homeowners insurance plus taxes add to the monthly payment?
- Is a seller credit reasonable given the flood risk disclosed?
Planting Roots With Eyes Open
Houston remains one of Texas's most dynamic markets, flood maps and all. The goal isn't to avoid flood zones altogether — plenty of well-built, properly elevated homes sit comfortably within them. The goal is to walk in with a full picture, so your monthly budget reflects reality, not just the loan estimate.
For buyers exploring financing options across the state, our Texas page offers a broader look at how local market conditions shape loan planning in different metros — Houston included.
Ready to make a plan?
- Start your plan: planpreparehome.com/apply
- Apply now: pph.pub/apply
- Call or text: 619-777-5700
Worth reading next: Houston Flood Insurance Requirements 2026: What FEMA's…, Tampa Bay Flood Insurance Cost by Zip Code… and DFW Windstorm Insurance Deductible Homebuyer Cost: What…. For the local picture, see our Texas page.