Colorado Hail Insurance Costs Home Buyer Pre-Approval 2026: What to Know Before You Shop
Yes — in Colorado, hail insurance can account for 26–54% of your total homeowners premium, and if it's not folded into your pre-approval conversation early, it can quietly shrink your buying power right before closing. That's the Colorado hail insurance surprise, and it's one of the most overlooked line items in 2026 home shopping.
Think of your pre-approval like a garden plan. You measure the sunlight, the soil, the space — then you pick what to plant. Skip measuring the soil (your insurance costs) and you might plant something that never quite takes root in your budget.
Why Hail Changes the Math
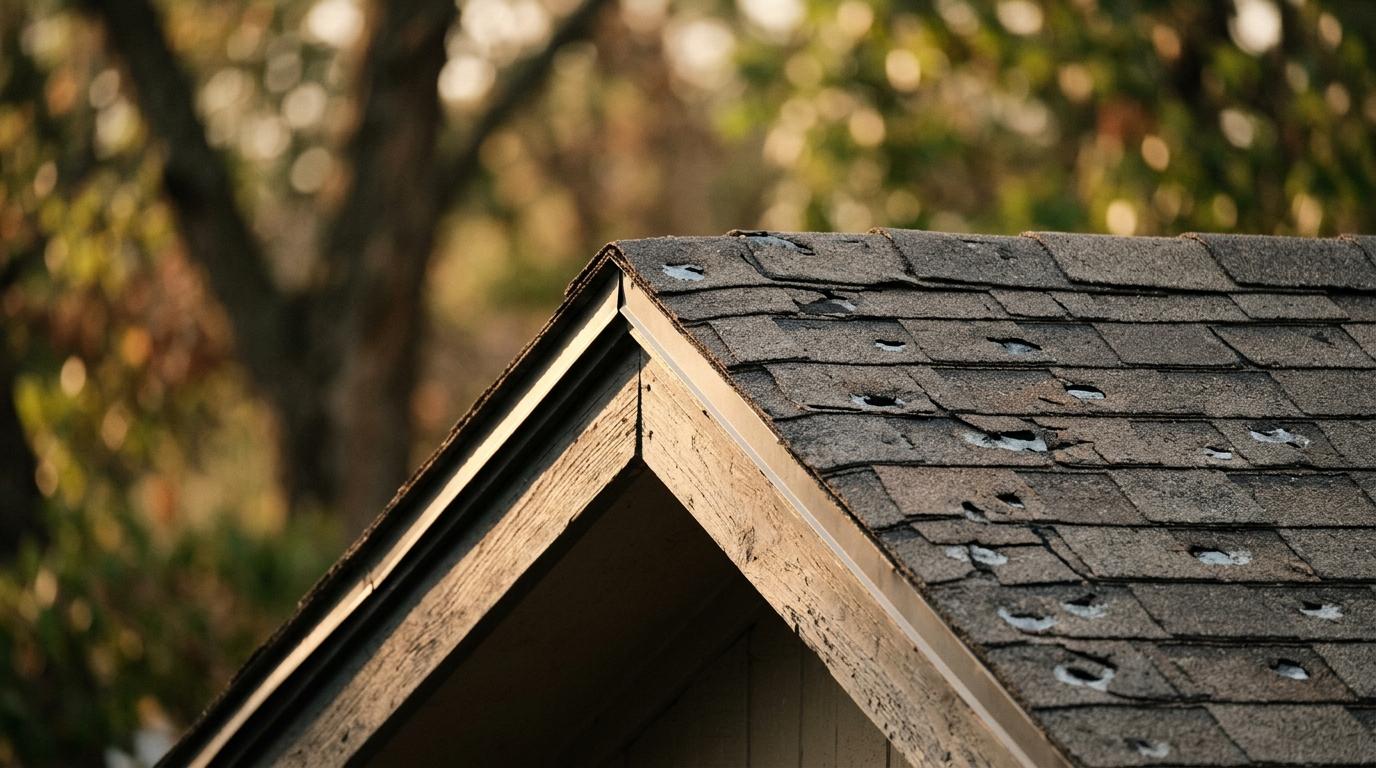
Most buyers budget for principal, taxes, and a rough insurance guess pulled from a national average. But Colorado's Front Range and eastern plains sit in one of the most hail-active corridors in the country. Insurers price for that risk heavily, and roof age is often the single biggest lever in the premium — sometimes more than square footage or claims history.
A newer roof (under 10 years) may qualify for standard coverage terms. An older roof can trigger higher premiums, percentage-based deductibles instead of flat ones, or in some cases, exclusions that require separate wind/hail riders. None of that shows up in a quick online insurance quote done before you've picked a house — it shows up when the underwriter runs your actual DTI with your actual premium, often weeks into the process.
The Percentage Deductible Trap
Here's where it gets tricky: many Colorado policies use a percentage deductible for wind/hail claims instead of a flat dollar amount — commonly 1% to 5% of the dwelling's insured value. On a higher-priced home, that can mean a deductible in the thousands, not hundreds. It doesn't change your monthly payment, but it does change your real cash cushion after closing, and smart loan officers factor that into the conversation about reserves, not just the payment itself.
How to Bake It Into Pre-Approval, Not the Closing Table
The fix isn't complicated — it's sequencing. Before your pre-approval number gets treated as gospel, have this conversation with your broker:
- Ask about roof age ranges, not just the city or ZIP code, when discussing target homes.
- Get a real insurance estimate, not a national average, once you're seriously looking at a property — insurance agents can often ballpark hail-zone pricing quickly.
- Build a buffer into your estimated monthly housing cost so a hail-zone premium doesn't blow past your comfort line.
- Ask about escrow cushion requirements tied to percentage deductibles, especially on homes priced above the local median.
This is where a brokerage earns its keep. Because Plan Prepare Home shops your loan across multiple lenders rather than offering just one in-house product, we can compare how different lenders weigh insurance estimates in their DTI calculations — some are more conservative than others, and that can matter when hail costs are real but still estimated.
Planting the Right Expectations Early
Roof age isn't the only seed to check, but in Colorado's hail corridor, it's one of the first. A 6-year-old architectural shingle roof and a 22-year-old three-tab roof on otherwise identical homes can carry very different insurance stories — and very different effects on what actually clears underwriting.
If you're house hunting anywhere along the Front Range, Western Slope, or the eastern plains, our Colorado page walks through state-specific considerations worth discussing with your broker before you write an offer — hail zones being one of several local quirks that shape the numbers.
The Takeaway
Hail insurance in Colorado isn't a reason to avoid a house you love — it's a reason to ask better questions earlier. Programs subject to qualification vary in how they treat insurance estimates and reserve requirements, which is exactly why shopping multiple lenders through a brokerage can surface options that fit your actual numbers, not just a generic pre-approval letter.
Measure the soil before you plant. In Colorado, that means asking about the roof before you fall for the view.
Ready to make a plan?
- Start your plan: planpreparehome.com/apply
- Apply now: pph.pub/apply
- Call or text: 619-777-5700
Worth reading next: Colorado Springs Insurance Costs Homebuyers 2026: Why…, How Much Does Hail Insurance Cost Denver Colorado Home… and Colorado Hail Insurance Cost for Homebuyers 2026: What…. For the local picture, see our Colorado page.